Pocketfolio Team
October 5, 2026
Most people weighing crypto funding rate arbitrage vs holding stablecoins think they are choosing between two different things. Often they are not.
A large share of stablecoin yield comes from this exact trade. Someone else runs it, keeps a cut, and hands you a token.
That does not make holding stablecoins the wrong choice. It does mean the real question is not which strategy is better, but whether you want to run the trade or pay someone to run it for you.
This guide covers what each option actually pays you for, where they overlap, how their risks differ in kind, and which one suits which reader.
Holding stablecoins pays you for lending, for supplying liquidity, for passing through interest on reserves, or for someone else running a hedged trade. You do nothing after the deposit.
Crypto funding rate arbitrage pays you for taking the unpopular side of a perpetual futures market while hedging away the price risk. You run it, watch it and close it yourself.
The honest answer for most people is stablecoins, because the work is the real cost and it is easy to underestimate. The honest answer for anyone willing to do that work is that the wrapper’s cut and the wrapper’s risks are both avoidable.
Neither is passive, and neither is safe. They are simply unsafe in different ways.
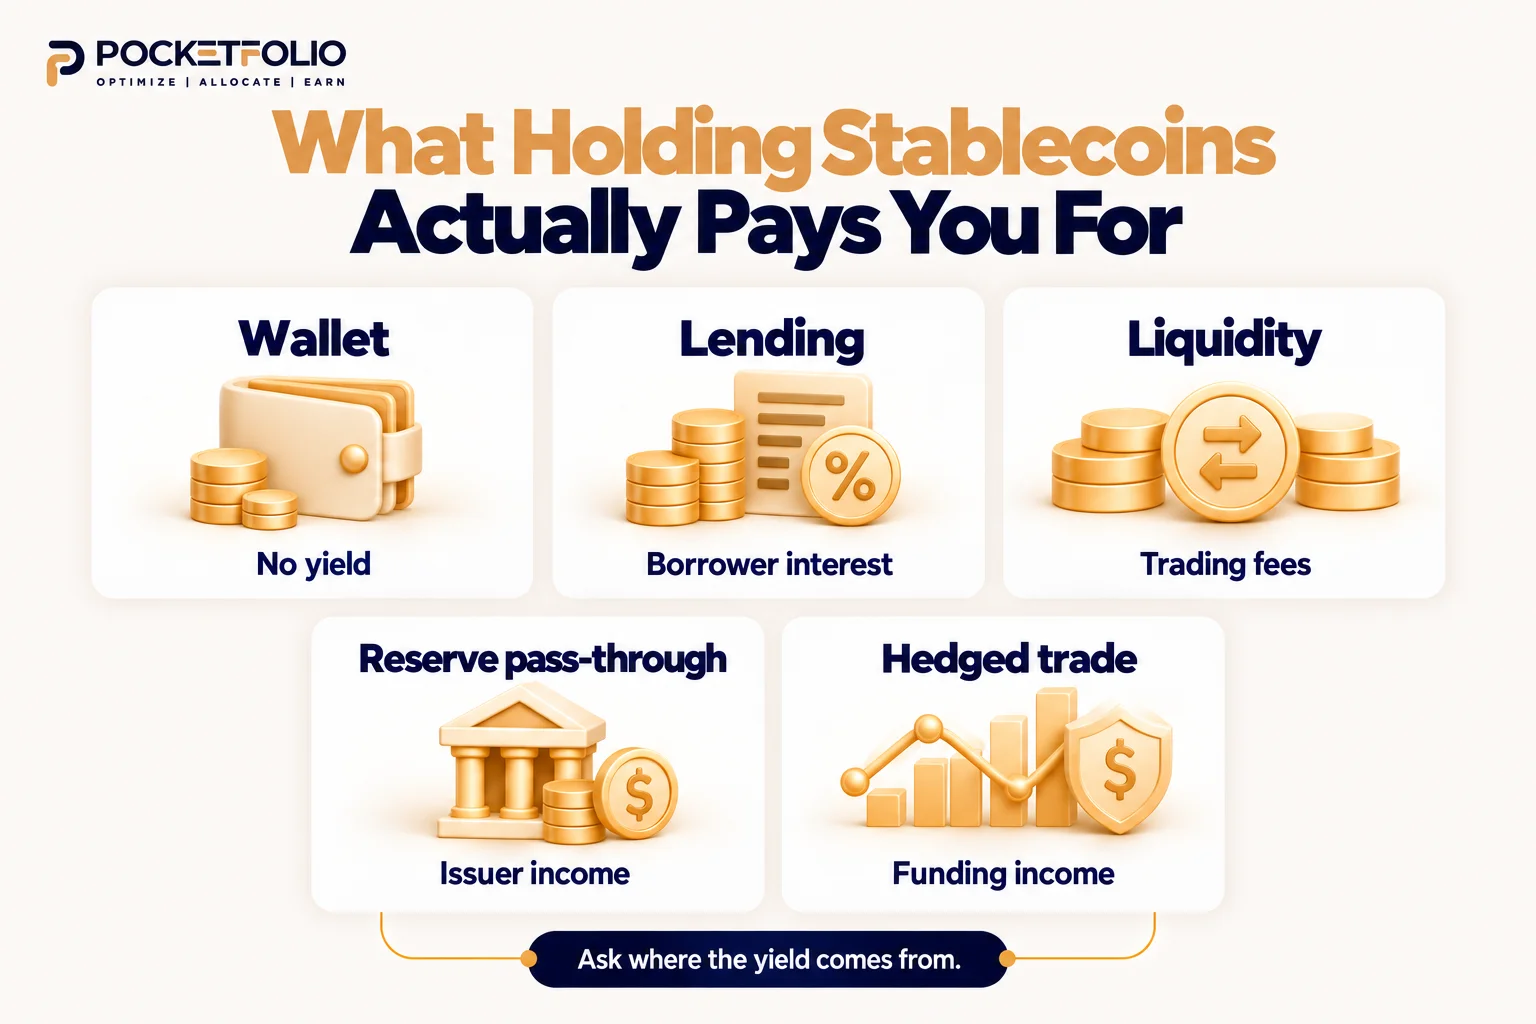
“Holding stablecoins” covers several unrelated things, and the risks depend entirely on which one you are doing.
Sitting in a wallet pays nothing. It is not a yield strategy, it is a decision to hold cash, and the only risk is the stablecoin itself.
Lending on a protocol pays you because borrowers pay interest. A lending protocol passes that demand through to you, and your risk is that the protocol breaks or borrowers default.
Supplying liquidity pays trading fees. Your risk is the pool mechanics rather than the dollar peg.
Interest pass-through pays you a share of what the issuer earns on its reserves. Your risk is the issuer and whatever it holds.
A yield bearing stablecoin built on a hedged trade pays you from a position someone else runs. That is the category this guide is really about.
Readers compare stablecoin yields as if they were one number with different sizes. They are different products with the same unit.
Two tokens paying similar amounts can carry completely different failure modes, because the yield is coming from different places. Loan demand, trading fees, treasury interest and funding income do not break at the same time or for the same reasons.
So the first question about any stablecoin yield is not how much it pays. It is what has to keep working for it to keep paying.
The trade holds long spot and short perpetual futures on the same asset at the same size. Price moves cancel between the legs, and the position collects funding while the rate stays positive.
You are being paid for taking the side of the market fewer people want. That is a service, and the payment is the market’s price for it.
This is a delta neutral position, which means it is designed to be indifferent to the coin’s price. It is not designed to be indifferent to everything else.
Our guide to how to make money with crypto funding rate arbitrage works through the income and the costs that eat into it.
Here is the part that reframes the comparison.
Several of the largest yield-bearing stablecoins generate their yield from exactly this trade. The protocol holds spot assets and shorts the matching perpetual futures, and the funding collected on the short leg is where the yield comes from.
Published breakdowns of stablecoin yield sources list basis trading and delta neutral strategies alongside lending, liquidity provision and treasury pass-through. It is a recognised category, not a fringe one.
So when someone holds that kind of token, they are already exposed to crypto funding rate arbitrage. They are simply exposed to it through an intermedia
It gives you no work. No venues to compare, no legs to open, no settlement times to be present for, no exit decision.
It gives you scale and access. The protocol runs size and venue relationships an individual cannot.
It costs you a cut. The spread between what the position earns and what holders receive is the fee, whether or not it is labelled as one.
It costs you control. You cannot close when you think the rate is about to flip, because you are not holding the position.
It adds risks that are not in the trade. Smart contract risk, the protocol’s own counterparty choices, and whatever happens to the token’s peg under stress.
That last point is the one people miss. Wrapping a hedged trade in a token does not remove the trade’s risks, it adds a layer on top of them.
| Holding stablecoins | Running the trade yourself | |
|---|---|---|
| Where the yield comes from | Lending, fees, reserves, or a hedged trade someone else runs | Funding paid by the crowded side of a perpetual market |
| Work after setup | None | Monitoring, settlements, exit decisions |
| Who decides when to exit | The protocol, or nobody | You |
| Fees you pay | A cut you usually cannot see | Four fills, plus transfers if any |
| Price exposure | None | None, while the hedge holds |
| Main failure mode | Protocol, issuer, or peg | Rate flip, liquidation on one leg, execution |
| Capital efficiency | Full deposit works | Depends on margin mode and buffer |
| Liquidity | Instant to locked, depending on product | Limited by how fast you can unwind both legs |
| Skill required | Very little | Real, and it compounds |
| Transparency | What the protocol publishes | Everything, because it is your position |
Read the exit row and the fee row together. That is the trade you are actually making.
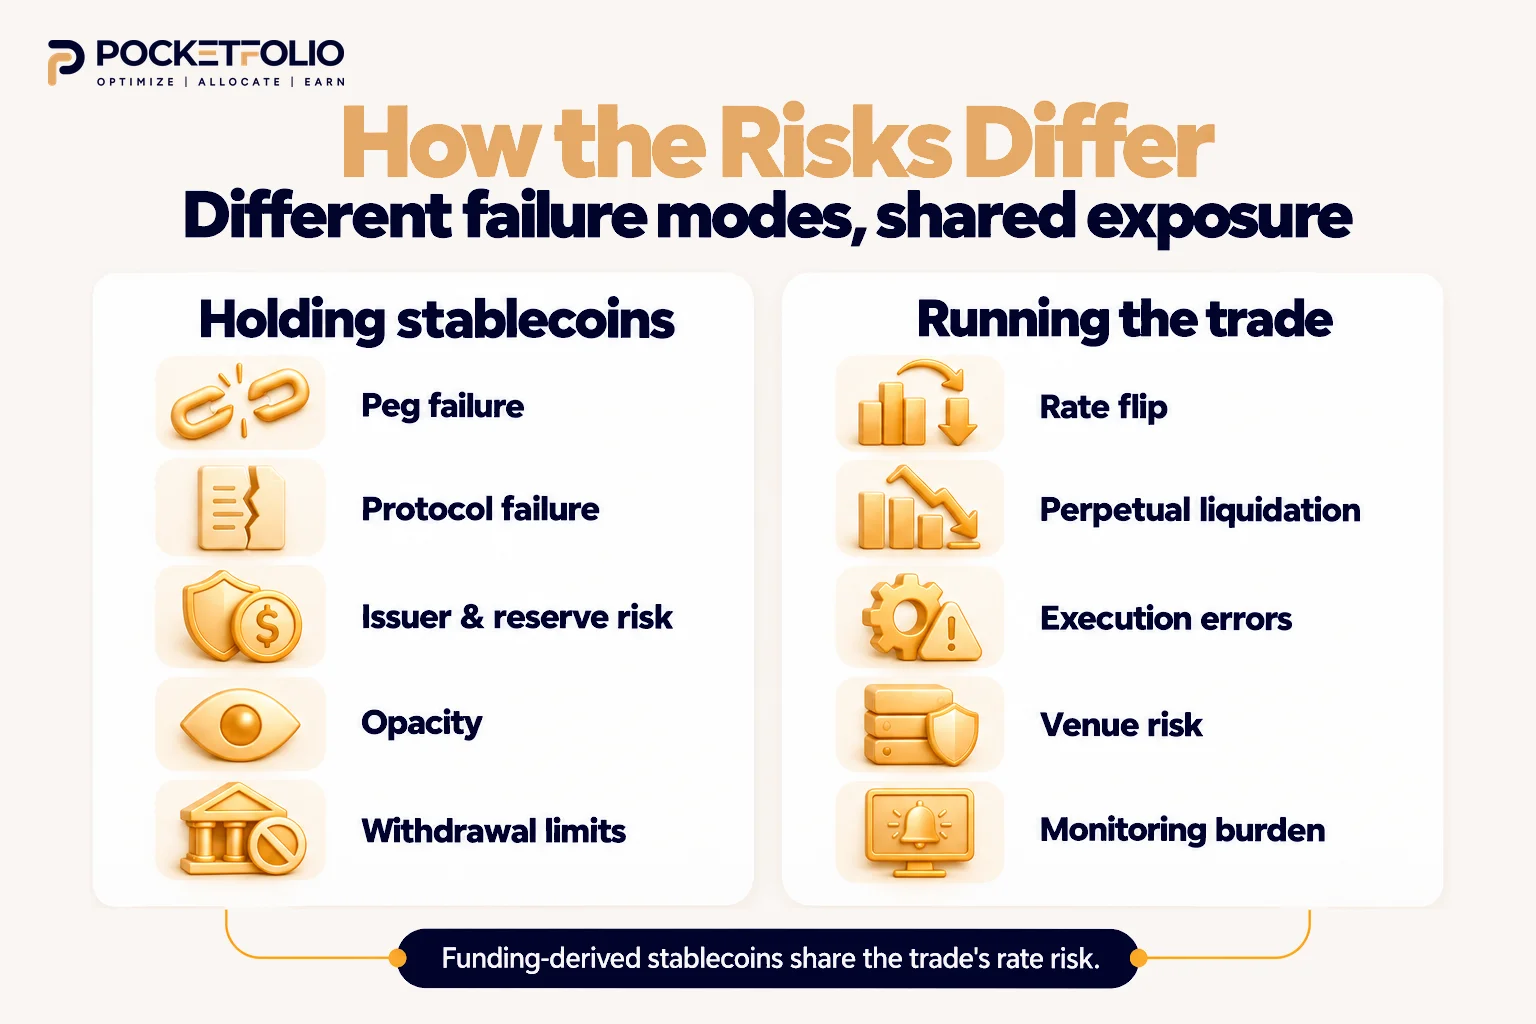
The risks are not bigger or smaller on one side. They are different in kind, which makes them hard to compare and easy to get wrong.
Peg failure. The dollar assumption is the whole product. A depeg does not reduce your yield, it damages your principal.
Protocol failure. Lending markets, liquidity pools and yield tokens all run on code that can break or be exploited.
Issuer and reserve risk. With pass-through yield you are exposed to what the issuer holds and how honestly it reports it.
Opacity. You usually cannot see the positions generating your yield, so you cannot judge them. You are trusting a report.
Withdrawal conditions. Some products lock capital, and others stay liquid until stress arrives and everyone wants out at once.
Rate flip. The income can turn into a cost, and you must be watching to notice. Our breakdown of when to close a crypto funding rate arbitrage position covers how to decide.
Liquidation on the perpetual leg. Delta neutral protects you from price direction, not from one leg being closed while the other sits elsewhere.
Execution. Legs opened apart, mis-sized, or filled at worse prices than you planned.
Venue risk. You are holding collateral somewhere, which is the same counterparty exposure a stablecoin holder has, just chosen by you.
Your own attention. The strategy fails quietly when nobody is watching it.
Pocketfolio’s honest breakdown of crypto funding rate arbitrage risk covers that second list in full.
Both routes depend on funding rates when the stablecoin yield comes from a hedged trade. Buying the token does not diversify away from the strategy, it just hides the exposure.
A reader holding that kind of token and also running the trade is doubling down on one source of income rather than spreading across two.
This is where the comparison is usually decided, and it is rarely stated.
Holding stablecoins costs you one decision and then nothing. Running the trade costs you a decision every day you hold it.
You compare venues before entering, and convert rates to a common period so the comparison means anything.
Then you watch for a flip, decide when to close, and do it again for the next position.
Our guide to how to track crypto funding rates across multiple exchanges covers the monitoring side.
That work is the thing the wrapper’s cut is paying for. Whether it is worth paying depends entirely on what your time is worth and whether you enjoy it.
Pocketfolio’s DIY Trading Scanner, a crypto funding rate arbitrage scanner covering 50+ venues, exists to shrink the comparison step rather than remove the job. Finding the rate is the part that automates well, and the deciding and watching still belong to you.
Neither the scanner nor any tool makes this passive. If passive is what you want, the honest recommendation on this page is a stablecoin product rather than a trade.
The two differ in how fast capital comes back, and in what makes it slow.
A stablecoin position can be instant or locked for a fixed term, depending entirely on the product. The lock is known in advance, which is useful.
A hedged position has no formal lock, and unwinding it still takes time. Two legs have to come off together, and if they sit on different venues a transfer sits between you and your cash.
So one has a stated lock-up and the other has an effective one. The effective version is harder to plan around because it depends on market conditions at the moment you want out.
Under stress both tighten. Books thin out exactly when you want to unwind, and stablecoin products see withdrawal queues for the same reason.
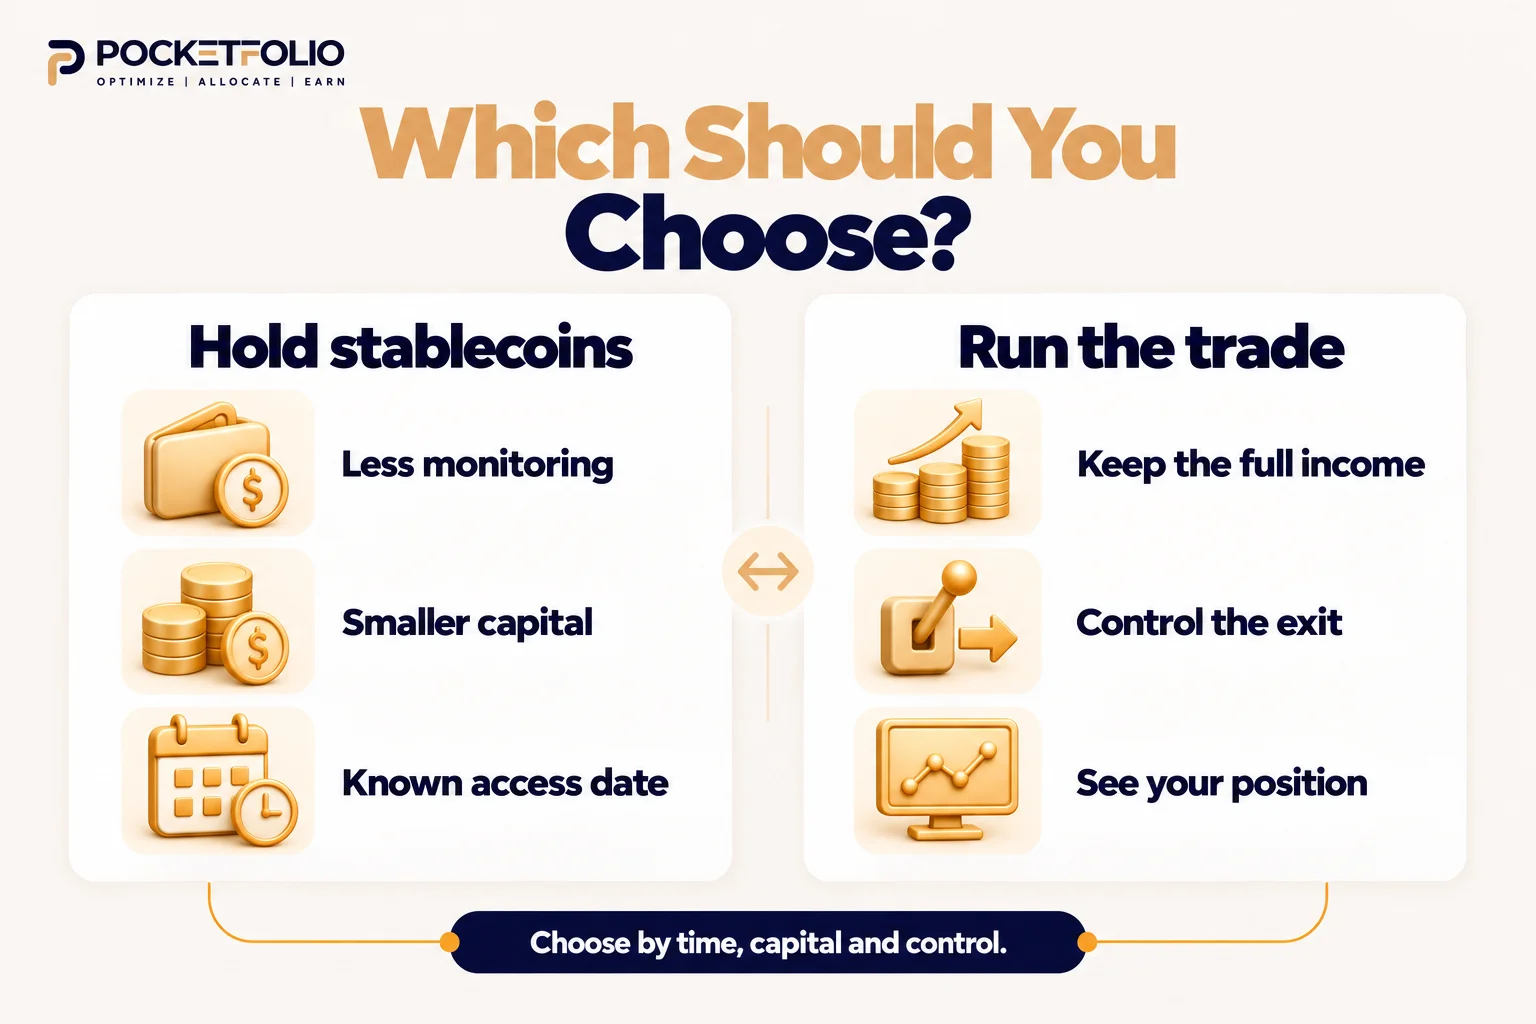
Choose stablecoins if you will not watch it. An unwatched hedged position is worse than an unwatched deposit, because it can turn from income into cost without telling you.
Choose stablecoins if your capital is small. Fixed costs decide whether the trade clears its own expenses, as our guide to how much capital you need to start crypto funding rate arbitrage works through.
Choose stablecoins if you need the money on a known date. A stated lock-up is easier to plan around than an unwind that depends on conditions.
Run the trade if you want the full income rather than what is left after a cut. That is the central argument for doing it yourself.
Run the trade if you want control of the exit. Holding the position is the only way to close when you decide rather than when a protocol does.
Run the trade if you want to see what you own. Your own position is fully visible. A wrapper’s is whatever it chooses to publish.
Yes, and most people who do it well treat the two as different jobs rather than competing options.
Stablecoin yield suits the capital you are not actively managing, including the buffer a hedged position needs but cannot deploy. That turns idle collateral from an opportunity cost into a small income.
The trade suits the capital you are prepared to watch.
One caution worth repeating. If the stablecoin product you hold earns its yield from a hedged trade, running the same trade yourself concentrates your exposure rather than diversifying it.
Check what your yield source actually is before assuming the two sit in different baskets.
Everything above depends on knowing which kind of yield you hold. Most readers do not, and the product page rarely says plainly.
Read the mechanism, not the marketing. A product describing itself as earning from market neutral positions, basis, or perpetual funding is running the trade this guide describes.
One describing borrower demand is a lending market, and one describing treasury or reserve income is pass-through.
Ask what has to keep working. Lending needs borrowers, liquidity provision needs trading volume, and pass-through needs the issuer’s reserves.
A hedged trade needs funding rates to stay positive and the hedge to hold.
Check whether the yield is fixed or variable. A fixed rate on a variable income source means someone is absorbing the gap, and it is worth knowing who and with what.
Check where the collateral sits. A hedged trade has to short perpetuals somewhere, usually on centralised venues, which means the product carries venue counterparty risk whatever its own branding says.
Check the withdrawal terms before you need them. Instant, queued, and locked are three different products, and the difference only matters on the day it matters.
Funding income varies. It can compress, and it can turn negative.
So a product paying a fixed return from that source is making up the difference somewhere when the source underpays. That might be a reserve, a subsidy, or new deposits.
None of those are automatically wrong, and all of them are worth understanding before you commit. If a product cannot explain where a fixed payment comes from when its income source is variable, that is the question to keep asking.
This is the one piece of diligence that applies no matter which side of the comparison you land on.
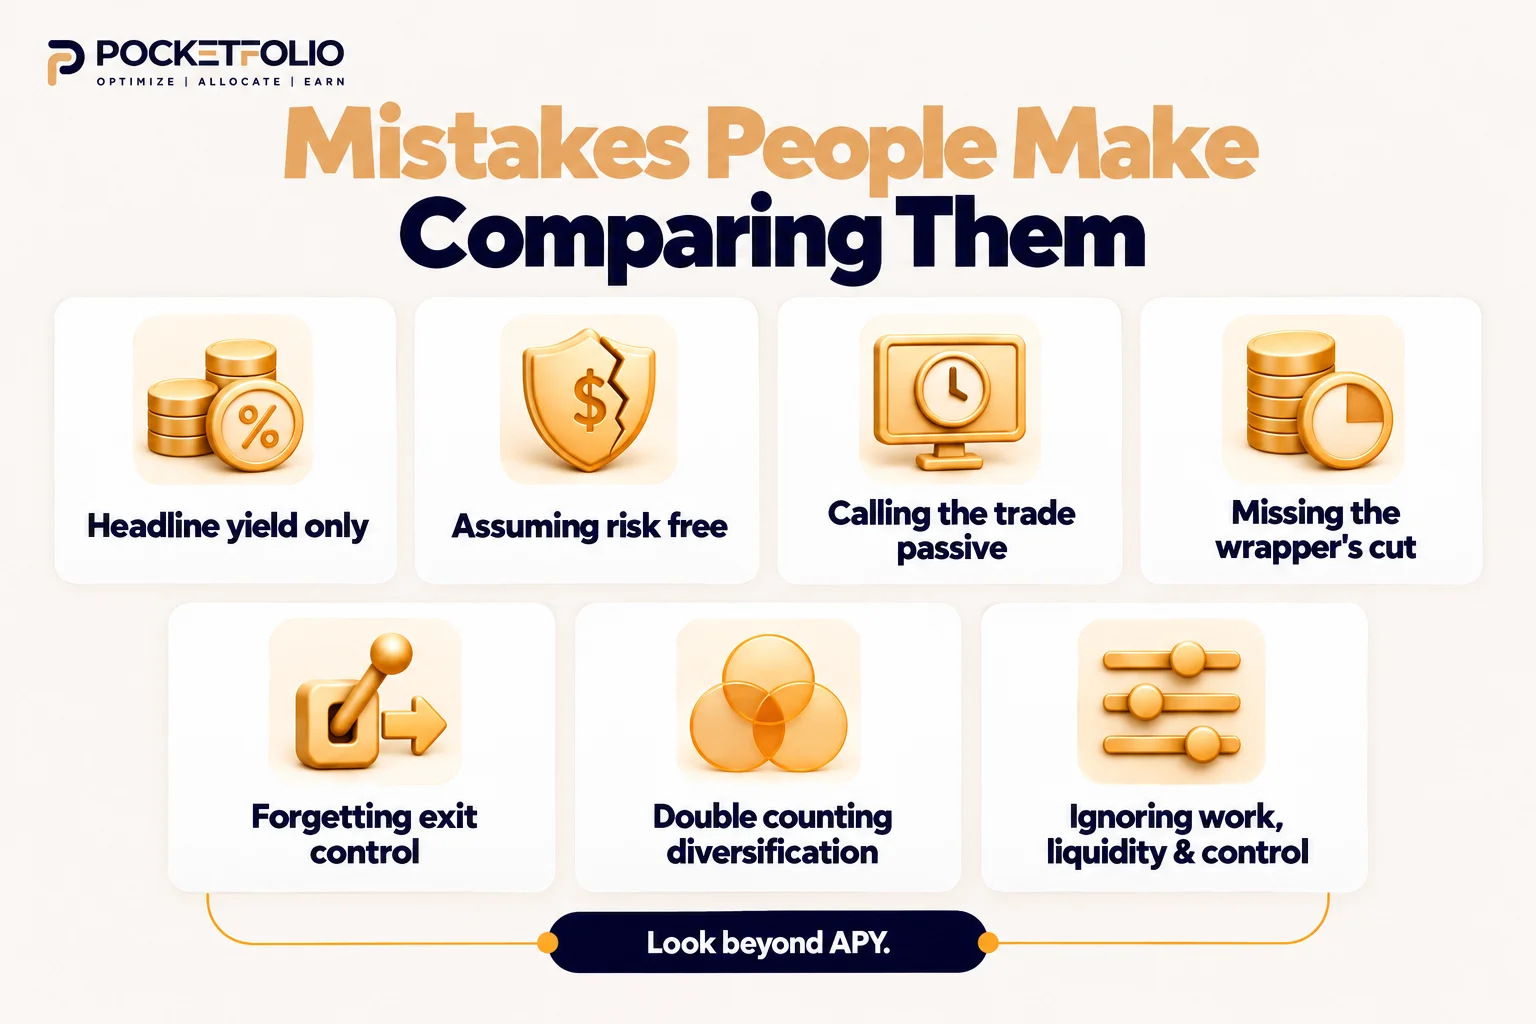
Comparing headline yields without comparing sources. Two similar numbers from lending and from a hedged trade are not the same product and do not fail the same way.
Treating stablecoin yield as risk free. The dollar assumption is a product feature, not a law. Peg and protocol risk are real and they hit principal rather than income.
Treating the hedged trade as passive. It is market neutral, which is a different claim entirely.
Ignoring the wrapper’s cut. The gap between what a position earns and what holders receive is a fee even when nothing is labelled as one.
Forgetting the exit belongs to someone else. With a wrapped product you cannot act on your own read of the rate.
Double counting diversification. Holding a funding-derived stablecoin alongside your own hedged position is one exposure, not two.
Comparing on yield alone. The deciding factors are usually work, liquidity and control, and none of those appear in an APY.
Neither is better in general, because they ask different things of you. Stablecoins suit capital you will not watch, and the trade suits capital you will.
Sometimes yes. Several yield-bearing stablecoins generate their yield from a hedged position collecting funding, which is the same trade packaged as a token.
To keep the cut the wrapper takes, to control the exit, and to see the position you own. In exchange you take on the work and the execution risk.
Neither, and the question hides the real difference. One carries peg, protocol and issuer risk; the other carries rate flip, liquidation and execution risk.
Yes. Fixed costs make small accounts hard to run profitably, while a stablecoin deposit has no equivalent floor.
No. The dollar peg is a design goal rather than a guarantee, and lending or yield products add protocol and counterparty risk on top of it.
A hedged position faces thin books and possible liquidation on one leg, while stablecoin products face withdrawal pressure and peg stress. Both tighten at the same time.
Yes, and it is a common setup, with idle capital and buffers earning while deployed capital runs the trade. Check your stablecoin’s yield source first so you are not concentrating one exposure.
If its yield comes from a hedged trade, yes, indirectly. That exposure is real even though you never open a position.
Stablecoins, because the work and the execution risk of the trade are both easy to underestimate before you have run it. Learn the mechanics first and size small when you do start.
Share this article
Share this article
Best Exchanges for Crypto Funding Rate Arbitrage
The best exchanges for crypto funding rate arbitrage are not
Is Crypto Funding Rate Arbitrage Still Profitable?
Is crypto funding rate arbitrage still profitable? In roughly a
Crypto Funding Rate Arbitrage in a Bear Market
Crypto funding rate arbitrage in a bear market does not
You may be interested in these blogs
Best Exchanges for Crypto Funding Rate Arbitrage
The best exchanges for crypto funding rate arbitrage are not the ones with the lowest fees or the deepest books.
Is Crypto Funding Rate Arbitrage Still Profitable?
Is crypto funding rate arbitrage still profitable? In roughly a tenth of the market, yes. In most of the rest
Crypto Funding Rate Arbitrage in a Bear Market
Crypto funding rate arbitrage in a bear market does not stop working. It gets smaller, and the version that replaces
Ready to Explore the Platform?
Explore AI-powered tools for analyzing arbitrage opportunities.
No fees. No risk. Cancel anytime.

Ready to Explore the Platform?
Explore AI-powered tools for analyzing arbitrage opportunities.
No fees. No risk. Cancel anytime.

New breakdowns on funding rates, arbitrage and market structure will arrive at your inbox.